Manufacturing
Scalable production and proprietary device development for plastic surgery and orthopedic demand.
A busy baby boomer, Carlos worried about visible scars, a “pulled” look, anesthesia and a long recovery, and med spa treatments couldn’t give him lasting results. He is one of millions: a multi-billion dollar gap affecting up to 90% of men and women, with no national solution.
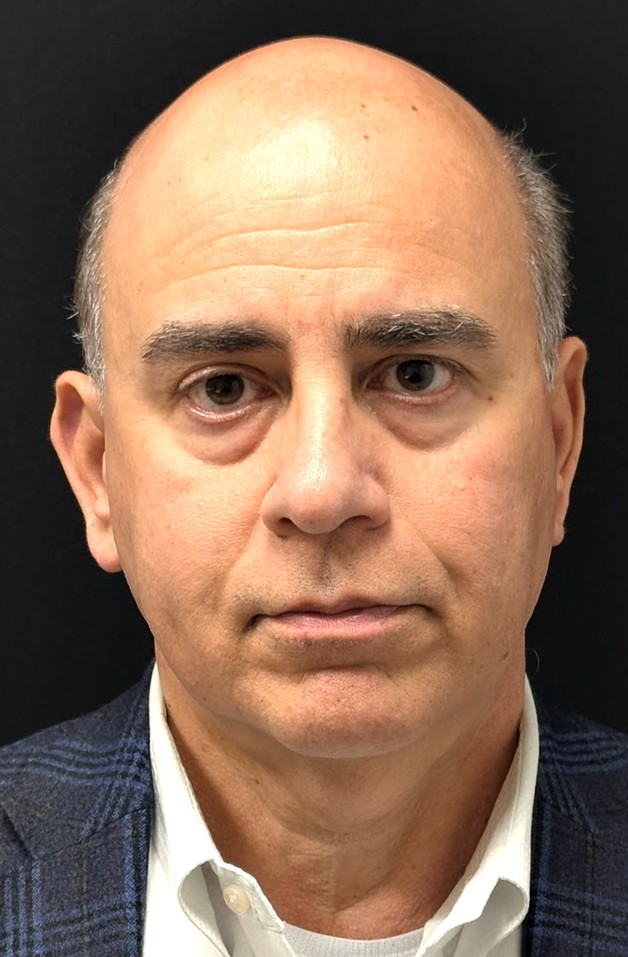 Before
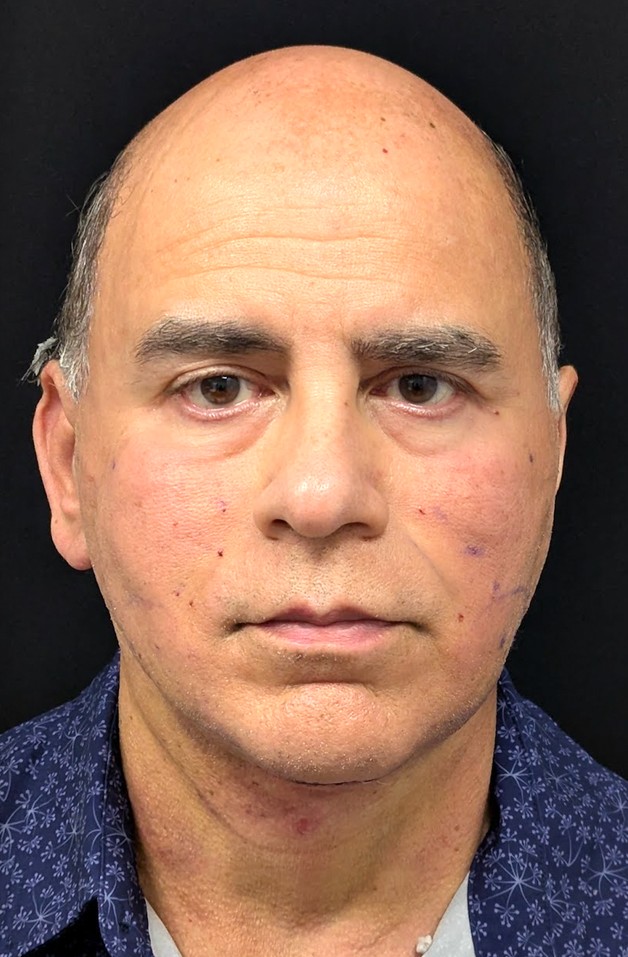 24 hours later
“Pretty remarkable. I really honestly didn’t think you would be able to take off all the saggy skin that was under my neck.”
Carlos · 24 hours after his procedureReLiftMD™ has developed minimally invasive ReLift® procedures using proprietary materials, performed in about an hour under local anesthesia. The founding surgeon has proven high patient satisfaction, high demand and highly favorable economics.
Board-certified plastic surgeons nationwide are joining, and have invested in the company. Accredited investors are now invited to accelerate the expansion, with prioritized distributions, a unique liquidity feature and equity in the national roll-up.
2025: $1.75 million in sales and $694,655 in operating profit from a single clinic.
The roll-up rests on two kinds of demand: patients who choose the ReLift® procedure and tell others about it, and board-certified plastic surgeons who want to offer it in their own markets. Hear both, in their own words.
Patient voices · 1:59. Patient stories are shared with written authorization and reflect individual experiences. Individual results vary. Patients were not compensated for their testimonials.
Founder’s Circle highlights · 1:24. Excerpts from a recorded Founder’s Circle meeting, August 2026, shared with the participants’ permission. Views are those of the individual surgeons.
Elective medical services are a $627 billion market, nearly half of it aesthetic. Laser vision and body contouring each built a national brand. Facial rejuvenation, with the highest margins of the three, has not.
| Category | US · Global | CAGR | National brand | Centers | Revenue | Margin | Margin influences |
|---|---|---|---|---|---|---|---|
| Laser vision correction | $3.8B · $9.1B | 8.1% | LasikMD | 600 | $148MM | 30% | High capex, recurring costs, competition |
| Body contouring | $4.0B · $5.7B | 6.8% | Sono Bello | 100 | $500MM | 35% | High capex, no moat, limited offerings |
| Facial rejuvenation | $12B · $54B | 10% | None yet | — | — | 65% | Low capex, protected moat, recurring revenue |
The global market was $83 billion in 2023 and $91 billion in 2024, and is forecast to reach $213 billion by 2034, growing about 9.7% a year.
Global market, US dollars. Straits Research (2024). 2025–2033 are interpolated at a constant annual growth rate between the 2024 base year and the 2034 forecast, for illustration.
Sources: Global Growth Insights, “Elective Healthcare Services” (2025); Business Research Insights; Market Research Future (2025); Tracxn; Straits Research (2024). Third-party estimates.
ReLiftMD™ manufactures ReLift® devices, drives patient traffic to partner surgeons, and exits through a national roll-up. Ancillary revenue comes from B2B and B2C product sales.
Scalable production and proprietary device development for plastic surgery and orthopedic demand.
A management services organization providing turnkey operations, marketing and compliance to partner surgeons.
Strategic acquisition and integration of high-performing elective medical clinics nationwide.
Each ReLift® Center uses the partner’s existing space, staff and OR capacity.
Partner surgeons invest $100K, and each Center brings about $1MM in pre-paid sales revenue a year.
A low-utilization asset-based credit line creates a liquidity flywheel for the roll-up and equity appreciation.
250 certified plastic surgeons, each performing four or more ReLift® procedures a month, with the ReLift® Business Network and patient membership programs.
A non-dilutive roll-up, with acquisitions powered by a revolving credit facility, unlocking institutional multiples by consolidating fragmented clinic earnings.
From ten clinics in year one to 250 by year five.

Capital funds the national expansion of 250 ReLift® Centers through the MSO and production of proprietary materials through Fabrication. Accredited investors may participate with $100,000.
Accredited investors join through the dedicated SPV.
100% of net profits go to investors first, targeting a 25% IRR over 3–5 years and a full return of capital.
Equity units carry a liquidation value equal to the initial investment, with redeemable-share liquidity.
An acquisition of Fabrication (5x floor) and a public exit of the MSO (10x+).
Simple arithmetic of the targeted multiples applied to the minimum investment. An illustration of the targets only, not a projection or a promise.
A cash-first structure distributes 100% of net profits to investors.
Preferential return of capital, plus a share of any upside.
Redeemable shares allow an exit with 100% return of capital, subject to liquidity.
Investors cannot be diluted by future small rounds.
Right of first refusal on future capital raises.
Confidential operating and financial updates.
Sell alongside major shareholders.
No additional capital is required after investment.
ReLiftMD Ventures, LLC, a Reg D 506(c) dedicated SPV, is raising $50MM. Phase I funds the national expansion of 250 ReLift® Centers and production of proprietary ReLift® materials. Phase II rolls up the clinics to unlock institutional multiples.
A dual revenue structure, device sales and MSO fees; procedures that require current ReLift® devices; a category growing above 10% a year; Centers expected to generate over $1MM annually each; and a model proven with over $32MM in revenue and 2,200 patients.
Investors are prioritized to receive distributions from operating cash flow, targeting a 25% IRR over 3–5 years with a full return of capital. Equity value is targeted through an acquisition of the manufacturing division and an IPO of the MSO.
Accredited investors may participate with $100,000.
Each Monday, Dr. Adam Summers and COO Curt Clinkinbeard walk through the track record, the five-year build and the offering, then take your questions live.